Should You Roll Over Your Intermountain Health Pension? What to Consider

If you are one of the Intermountain Health caregivers who earned a pension, this decision probably feels personal, and it should. You put in years of work for this benefit, and with the plan freeze on the horizon, the question of what to do with it has gone from someday to soon.

It is also a decision with real consequences for your income. Taxes, your spouse, Social Security, healthcare costs, and how long you live all shape whether it makes more sense to keep the pension as a monthly check or move its value into an account you control.

How the Pension Freeze Changes the Decision

Intermountain Health announced that its pension plan will be frozen on December 31, 2026. If you are still participating, you continue to earn benefits up to that date, and the benefits you have already earned remain yours, held in a trust and protected by federal law.1

Because the pension stops growing after the freeze, your 401(k), personal savings, and other accounts may need to carry more of the weight they used to share with the pension. That shift is worth planning around now rather than later.

It also brings the rollover question to the fore. Depending on the plan’s rules, you may be able to take your earned benefit as monthly payments or move its lump-sum value into a retirement account you manage. Knowing what job that benefit is meant to do in your income plan is the first step.

What Rolling Over Your Pension Actually Changes

A rollover moves your pension’s value out of the plan and into a retirement account you own, if the plan allows it. In exchange for that control, more of the responsibility for investing, tax timing, and disciplined withdrawals lands on you.

Here is what actually shifts when you roll it over:

It becomes money in a retirement account. Your lump-sum value can be transferred to an individual retirement account (IRA) or another qualified plan. When done as a direct rollover, the move is generally not taxed in the year it happens.

A guaranteed check turns into an investment you manage. Instead of a fixed monthly amount, you hold a balance that rises and falls with the markets, so its investment mix should match the income job you need it to do.

You take over the withdrawals and the tax timing. You decide how much to pull, when, and from where, which opens your options to coordinating withdrawals, Roth conversions, and charitable giving, but also makes the planning your responsibility.

Whatever is left can go to the people you choose. Money you do not spend can pass to heirs, your church, or other causes, which a monthly pension usually cannot do once payments stop.

It adds a future required-withdrawal obligation. Once your money sits in a pre-tax IRA, required minimum distributions (RMDs) will eventually force taxable withdrawals whether you need the money or not.2

It is hard to undo. Once your rollover is processed, you generally cannot switch back to your monthly pension, so this is close to a one-way door.

Please Note: How your money moves matters as much as the decision to move it. If your pension is paid directly to you rather than transferred directly to your new account, the plan must withhold 20%, and you have only 60 days to complete your rollover.3 Any amount that misses that window can be taxed and, if you are under 59½, hit with an extra 10% penalty.4

Compare a Monthly Pension and a Rollover by What You Need

At its core, this is an income decision. The real question is which option better supports your expenses, taxes, giving, spouse, and the years of retirement ahead.

A monthly pension buys predictability and simplicity, while a rollover buys control, tax flexibility, and access to whatever you do not spend. Neither is automatically better, so the right fit depends on your preference.

When a Monthly Pension May Fit Better

A monthly pension tends to be a good fit when you value steady income and would rather not manage a large balance yourself. It works like a paycheck for life, covering your basic bills without you having to make investment calls.

A monthly pension may be the better fit when:

  • You want a dependable income floor for your fixed expenses.
  • Market swings make you uneasy, and you would rather not worry about them.
  • You want income that is guaranteed to last as long as you do.
  • You already have enough saved elsewhere for emergencies, taxes, and anything you want to leave behind.
  • A survivor option can protect your spouse’s income after you are gone.

When a Rollover May Fit Better

A rollover tends to be a good fit when you want more say over how the money is invested, taxed, spent, and eventually passed on. The tradeoff is that your broader plan has to shoulder that responsibility.

A rollover may be the better fit when:

  • You want the freedom to take more in some years and less in others.
  • You want control over your taxable income, including Roth conversion windows.
  • You want whatever is left over to be available for heirs or giving.
  • You want growth potential, so your income keeps up with inflation.
  • You have the discipline and experience to manage it, or an advisor to help.

Risks to Weigh Before You Roll Over

A rollover can be the right move, but the flexibility comes with tradeoffs worth testing first. Once the money is yours to manage, it has to keep paying you through market drops, tax surprises, a long retirement, and your spouse’s needs too.

Before you choose a rollover, pressure-test these risks:

Investment risk. Once your money is invested, it rises and falls with the markets, your fund choices, and fees. If it becomes a main source of income, even a reasonable mix can feel uncomfortable in a downturn.

Sequence-of-returns risk. A rough market in your first retirement years does more damage than the same drop later, because you are selling while balances are down. Test whether the account can recover while still paying you.

Longevity and inflation. Your money has to last a long time and keep up with rising costs, especially healthcare costs, over a retirement that could last three decades. A pace that feels fine at first can fall behind if you live long or prices climb.

Tax stacking. Pre-tax withdrawals, Roth conversions, taxable Social Security, and required withdrawals can all land in the same year and push you into a higher bracket, shrinking what you actually get to spend.

Overspending. Easy access is a double-edged sword. It helps with a surprise repair or medical bill, but without guardrails, it can invite spending faster than the plan can handle.

Spouse and survivor income. Map what your household keeps if one spouse dies. A rollover can leave a balance behind, while a pension’s survivor choice affects how much the monthly check is and how much continues for your spouse.

Behavioral risk. Downturns tempt even seasoned investors to sell low or chase returns after a loss. A written plan you agree to in advance takes some of the emotion out of those moments.

Coordinate the Choice With the Rest of Your Retirement

Your decision does not happen in a vacuum. The better option can flip once you factor in your Social Security timing, taxes, 401(k), Roth accounts, and cash reserves.

Think of each of your income sources as having a job. One provides a stable income, another covers flexible spending, and another helps with taxes, emergencies, growth, or the protection of your spouse. Your pension choice should fit the role you need it to play among them.

Social Security Timing

Social Security often matters more than people expect because when you claim it, it changes the size of your check for the rest of your life. Claiming before your full retirement age permanently reduces the monthly benefit, while waiting can grow it, right up until age 70.5

That timing decides how much pressure falls on your pension or portfolio early on. If you delay Social Security for a larger check later, you may lean more on a pension payment, your 401(k), or cash reserves to bridge the gap in the meantime.

A larger Social Security benefit can make a rollover easier to carry, since it covers more of your baseline spending for life. A smaller or earlier benefit can make a steady pension more valuable, especially for a surviving spouse who may rely on it.

Healthcare Costs and Medicare

Your health coverage and its costs affect both your spending and your taxes once you retire. Timing the transition well takes some planning.

A few healthcare and tax points deserve attention here:

  • If you retire before 65, you will need to bridge to Medicare. Weigh retiree coverage, Consolidated Omnibus Budget Reconciliation Act (COBRA) continuation, a marketplace plan, or a spouse’s plan, and remember that Medicare enrollment has its own timing rules once you reach 65.6
  • Large withdrawals or Roth conversions raise your taxable income, which can ripple outward: increasing how much of your Social Security is taxed and lifting your future Medicare premiums, which are tied to your income from two years earlier.7
  • Cash reserves can cover uneven medical costs without forcing a taxable withdrawal. That helps most when your income is already high in a year.
  • Roth accounts can fund needs without adding to your taxable income, which is useful in years with big medical bills or other one-time costs.

Your 401(k), Roth, Cash, and Other Savings

Finally, look at your accounts that fill gaps and absorb shocks. Strong savings make either pension choice easier; thin savings make the decision more delicate, because the pension may need to do more.

Take stock of what surrounds the pension:

Your 401(k) and employer contributions. Count your 401(k) balance and any employer match or contributions, since these accounts are set to carry more of the load once pension accruals stop.

Pre-tax balances and future taxes. A rollover into a pre-tax IRA increases the balances that will someday trigger required withdrawals, so it is worth considering how that affects your future tax picture.

Roth accounts. Qualified Roth withdrawals are tax-free, giving you a valuable lever to pull in tax-sensitive years.

Taxable and cash accounts. Taxable accounts and cash reserves can fund early retirement or emergencies and ease the pressure to sell investments at a bad time.

Numbers to Gather Before You Decide

When you are ready to run this for real, gather your actual numbers. Rough guesses about spending, taxes, and how long you will live can strain the plan later.

Before you choose, pull together and compare the following:

  • Your pension estimate, including both the monthly amount and the lump-sum value, so that you can weigh guaranteed income against the investable total.
  • Survivor options and how each one changes the monthly check and your spouse’s income.
  • Your real income needs to cover expenses once the paychecks stop, including fixed costs, taxes, giving, travel, and irregular expenses like home and vehicle repairs.
  • Social Security estimates for both spouses at different claiming ages.
  • Your 401(k), IRA, Roth, taxable, and cash balances, plus what you can still add while working.
  • Your current investment mix and how much risk it can handle, since a rollover needs both near-term stability and long-term growth.
  • A tax projection that lays out pension income, withdrawals, Roth conversions, required withdrawals, and Medicare thresholds.
  • Your health picture and any legacy goals, since both can change how much you value access, flexibility, and leaving money behind.

Rolling Over Your Intermountain Health Pension FAQs

1. Should I roll over my Intermountain Health pension?

It depends on what you need the pension to do. A rollover makes sense if you want control over the money and its taxes; keeping the monthly payments makes sense if you want steady, predictable income you do not have to manage.

2. Is a lump-sum rollover better than monthly pension payments?

Neither is better on its own. A lump sum gives you flexibility and access, while monthly payments give you a predictable income floor for life. The right choice comes down to your income needs, taxes, spouse, and how long you expect retirement to last.

3. Will rolling over my Intermountain pension create taxes?

A direct rollover into an eligible retirement account generally keeps the money tax-deferred, so no tax is due in the year you roll it over. Taxes come later, when you withdraw from a pre-tax account, or sooner if the money is paid to you or converted to a Roth account.

4. What are the biggest downsides of taking monthly payments instead of rolling over?

You give up flexibility, control over your tax timing, and the ability to leave what is left to family, and a fixed payment can lose purchasing power to inflation over a long retirement. For households that need dependable income, that stability can still be well worth it.

5. How does Social Security timing affect the pension decision?

Social Security determines how much income you still need from your pension or portfolio. If you delay it for a bigger check later, you may lean more on the pension or savings in the early years; if you claim early, more pressure lands on your income sources sooner.

6. Should I roll my pension into an IRA or another retirement account?

That depends on the investment options, fees, distribution rules, and how each choice fits your spouse and your other accounts. It is worth comparing an IRA against your 401(k) and any other eligible plan before you move anything.

Get Help Deciding Whether to Roll Over Your Intermountain Health Pension

Choosing between a lump sum and monthly pension payments affects your income, flexibility, taxes, spouse’s security, and long-term peace of mind. The best answer is the one that fits the life you want after work, not a rule of thumb.

At Peterson Wealth Advisors, we help you weigh your pension options alongside Social Security timing, healthcare costs, taxes, investment risk, and your spouse’s needs, and we lay out the choices side by side so you can see the trade-offs clearly.

From there, we can build a coordinated plan that puts your pension, 401(k), Roth accounts, cash reserves, and every other piece to work together. To see how your Intermountain pension could fit, schedule a conversation with our team.

Resources:

1) Intermountain Health Pension Plan Announcement

2) Retirement Plan and IRA Required Minimum Distributions FAQs

3) Rollovers of Retirement Plan and IRA Distributions

4) Exceptions to Tax on Early Distributions

5) Social Security Benefit Reduction and Delayed Credits
6) When Can I Sign Up for Medicare?

7) Medicare Premiums for Higher-Income Beneficiaries

When Should You Take Action on Your Pension? – Timing Your Intermountain Health Decision

Once you’ve decided what to do with your Intermountain Health pension — lump sum or monthly payments — the next question becomes just as important:

When should you act?

Timing can meaningfully impact the size of your benefit, your tax situation, and the long-term success of your retirement income plan. Let’s walk through the key considerations.

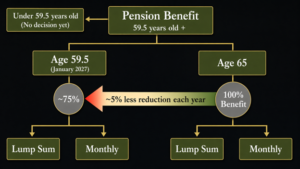
Understanding the 5% Rule

For caregivers between the ages 59½ and 65, your pension benefit is adjusted by roughly 5% per year. If you claim early, your lump sum or monthly benefit is reduced by about 5% for each year before age 65. For example:

  • Claiming at 65 = full value
  • Claiming at 62 = roughly 15% reduction
  • Claiming at 59½ = roughly 25% reduction

On the surface, that makes waiting look like the obvious choice. But timing is rarely that simple.

The Core Question: Can You Beat 5%?

If you’re considering taking the lump sum before age 65, the real financial question becomes:

Can you reasonably earn more than 5% annually by investing that money?

If you believe (and can structure your portfolio) to achieve returns above 5% over time, taking the lump sum earlier may make sense. That way, instead of accepting the guaranteed 5% annual increase by waiting, you’re putting that capital to work immediately.

If retirement is still a few years away, time is still on your side. That lump sum can potentially grow within a 401(k) or IRA while you’re still working. But this requires:

  • Discipline
  • Proper asset allocation
  • Long-term perspective
  • Thoughtful tax planning

Without a clear strategy, chasing returns simply to “beat 5%” can backfire.

The Case for Waiting Until 65

There’s also a strong argument for patience. If you wait until 65:

  • You receive the maximum pension value
  • You avoid the early-claim reduction
  • You lock in guaranteed growth

For someone who prefers certainty or who is nearing retirement and doesn’t want market exposure, waiting can provide peace of mind.

The guaranteed 5% annual increase until 65 is difficult to ignore, especially in a low-risk context. If you know you’ll need the income soon, maximizing the base benefit may be the wiser move.

Timing Monthly Payments: A Tax Consideration

Now let’s talk about monthly payments. Intermountain allows you to start receiving pension income while still working. That flexibility is unique — but it doesn’t automatically mean it’s wise.

Here’s a rule of thumb:

If you don’t need the income, don’t take the income.

Why?

Because if you’re still earning wages, pension payments stack on top of your salary. That can push you into higher tax brackets and reduce overall efficiency. You’re essentially accelerating taxable income you may not yet need. Waiting until retirement (when your earned income drops) often creates more tax flexibility.

The Bigger Picture: This Decision Is Not Isolated

Timing should never be evaluated in a vacuum. You must consider:

  • Your planned retirement age
  • Your other retirement savings
  • Social Security timing
  • Medicare eligibility
  • Current and future tax brackets
  • Your overall income needs

For example, if you plan to work until 67 and have other conservative assets, taking the lump sum early and investing it may allow it to grow more efficiently than waiting. But if retirement is just around the corner and you’ll rely heavily on the pension, maximizing the guaranteed amount may be the better fit.

This is not simply a math problem. It’s a coordination problem.

A Practical Framework

Here’s a helpful way to think about it:

  • If you can earn more than 5% annually, don’t need the income now, and are comfortable with market volatility — taking the lump sum earlier may make sense. 
  • If you prefer guaranteed growth, will need income soon, or value simplicity — waiting until 65 maximizes the pension benefit.

Both paths can be appropriate. The key is aligning the timing decision with your broader retirement income plan.

Ultimately, timing your pension decision is one of the most financially impactful choices you’ll make in the coming years. Early action offers growth potential and flexibility. Waiting offers certainty and maximum guaranteed value.

But the right answer depends on your full financial picture, not just the 5% rule. Before making a decision, it’s worth modeling both scenarios within a comprehensive retirement income strategy.

Peterson Wealth Advisors is a registered investment adviser. Information presented is for educational purposes only. Please consult a qualified financial advisor before implementing any strategy.

Lump Sum or Monthly Pension? – A Deeper Look at Your Intermountain Health Decision

One of the biggest decisions Intermountain Health caregivers will face as a result of the pension freeze is this:

Should I take the pension as a lump sum — or as monthly payments?

It’s a simple question on the surface. But underneath it are issues of inflation, taxes, flexibility, legacy planning, and personal responsibility. Let’s walk through both options carefully.

The Case for Monthly Payments

Taking your pension as a monthly income stream (annuitizing) provides something many retirees value highly:

Stability.

You receive a steady payment every month for the rest of your life. There are no market swings to monitor. No allocation decisions to make. No concern about running out of money tied specifically to that pension.

For some caregivers, that simplicity brings peace of mind. That monthly pension payment can feel like a safe harbor if you:

  • Strongly dislike market volatility
  • Don’t want to manage investments
  • Prefer predictability over flexibility
  • Or don’t have trusted guidance to help navigate downturns

But that stability comes with trade-offs.

The Limitations of Monthly Payments

The most significant challenge retirees face today is inflation. Your pension payment is fixed.

If you retire with a $3,000 monthly benefit, you’ll still receive $3,000 twenty years later. But if inflation averages 3% per year, the groceries, travel, healthcare, and everyday expenses that cost $3,000 today could cost roughly $5,400 per month in twenty years. In other words, the fixed payment stays the same, but it certainly loses purchasing power over time.

There’s also limited flexibility:

  • You receive the same amount whether you need it or not.
  • It restricts certain tax planning strategies.
  • You cannot adjust withdrawals based on changing circumstances.
  • When you and potentially your spouse pass away, the payments stop.

There is generally no remaining asset to pass to children or charities. That’s not necessarily wrong, but it’s important to understand what you’re giving up.

The Case for the Lump Sum

With the lump sum option, instead of receiving a monthly pension check for the rest of your life, you receive a one up-front payment that represents the estimated value of those future monthly payments.

Importantly, this does not necessarily mean the entire lump sum becomes taxable income to you immediately. If handled properly, the lump sum can typically be rolled into your 401(k) or IRA, allowing the money to remain tax-deferred until you begin taking withdrawals.

Taking the lump sum shifts you into the driver’s seat. You can roll it into your 401(k) or IRA and integrate it into your broader retirement income plan. This provides:

  • Investment control
  • Tax planning flexibility
  • Inflation-fighting growth potential
  • Legacy planning opportunities

The tax planning flexibility is often overlooked. By rolling the lump sum into an IRA or 401(k), you may have more control over when the money becomes taxable. That can open the door to more thoughtful tax planning around withdrawals, Roth conversions, Medicare premiums, and charitable giving. For caregivers who regularly give to charity or to their Church, this flexibility can be especially meaningful and allow you to withdraw from your IRA tax-free later in retirement.

Properly managed, a lump sum can be invested in a way that allows part of the portfolio to grow over time. That growth can help offset inflation and give you the ability to increase your income over the years as expenses rise. It also gives you more control over how much income you take, when you take it, and which accounts to draw from.

And if something happens to you or your spouse, the remaining assets don’t disappear. They pass on to heirs. For caregivers who value flexibility and legacy impact, that can be meaningful.

The Responsibility That Comes with Control

Here’s the honest truth: A lump sum is powerful, but it requires discipline. When you take control of that pension value, you are responsible for:

  • Investment allocation
  • Managing volatility
  • Withdrawal strategy
  • Tax efficiency
  • Ensuring the funds last throughout retirement

Without a plan, flexibility can turn into pressure. The pressure of making investment decisions, managing withdrawals, and wondering whether your money will last. With a structured retirement income plan, flexibility becomes strength. The key isn’t just taking the lump sum, but knowing how it fits into your broader retirement architecture.

Can You Create Stability Without the Pension?

Some caregivers assume the pension is the only way to create stable income. That’s not necessarily true.

A properly structured retirement income plan can generate a “paycheck” style income stream — while still maintaining flexibility and long-term growth potential.

And unlike a fixed pension, that income strategy can adjust if life changes. If:

  • Healthcare needs shift
  • Travel plans expand
  • Markets fluctuate
  • Family circumstances change

A dynamic plan can evolve. A pension cannot.

So… Which Is Better?

The answer depends on you. Your:

  • Comfort with volatility
  • Health and longevity expectations
  • Other income sources (Social Security, spouse’s benefits, 401(k))
  • Tax situation
  • Desire to leave a legacy
  • Willingness to engage in planning

There is no universal right answer.

But there is a right answer for your situation.

Final Thoughts

The pension freeze has forced caregivers into an important decision.

Monthly payments offer simplicity and predictability.

A lump sum offers flexibility and long-term potential.

The key is not simply choosing one or the other — but understanding how that decision supports your ability to create an inflation-adjusted stream of income that lasts throughout retirement.

If you’d like help weighing the pros and cons in the context of your full retirement picture, we’re happy to walk through it with you.

Peterson Wealth Advisors is a registered investment adviser. Information presented is for educational purposes only. Please consult a qualified financial advisor before implementing any strategy.

What Would a Financial Advisor Do? – A Personal Perspective on the Intermountain Health Pension Decision

If you’re facing the Intermountain Health pension decision, you’ve probably asked yourself:

“What would a financial advisor actually do in my situation?”

It’s a fair question. After all, advisors understand markets, taxes, income planning, and retirement risks. So if we were personally in your shoes — lump sum or monthly pension — what would we choose?

Let me give you an honest answer.

My Personal Lean: Control and the Lump Sum

If I were making this decision for myself, I would take the lump sum almost nine times out of ten. Why? Because I like having control over my money.

I’m comfortable with market volatility. I believe in long-term investing. And I trust my ability to stay disciplined — not to panic in downturns and not to overspend in the early years of retirement.

Taking the lump sum would allow me to:

  • Invest strategically
  • Create an income stream tailored to my needs
  • Adjust that income over time
  • And leave something meaningful behind for my family

With the right retirement income structure in place, I could design a monthly paycheck that potentially grows over time — something a fixed pension payment cannot do. And at the end of my life, there would still be assets remaining for the next generation. That’s compelling.

Another Advisor’s Take: Rollover With a Plan

Other advisors on our team share a similar perspective, but with nuance. One approach many advisors would take is:

  • Roll the lump sum into the Intermountain 401(k) initially
  • Keep it there while still working
  • Then consider moving it to an IRA at retirement

Why? Most 401(k) plans are built primarily for accumulation. They are designed for younger employees building wealth. The majority of investment options are stock-based.

When retirement begins, the focus shifts from accumulation to distribution. And that often requires more conservative and flexible tools than a typical 401(k) lineup provides. So while rolling to the 401(k) may be efficient while working, transitioning to an IRA later can allow for:

  • Broader investment flexibility
  • More conservative income-focused options
  • Greater distribution control

Again, the common theme is control paired with planning.

The Important Caveat

Despite our take on it, the lump sum is not automatically the right answer. If you:

  • Strongly dislike market volatility
  • Know you won’t stay disciplined during downturns
  • Tend to spend aggressively
  • Don’t have a structured income plan

The lump sum can become a problem instead of an opportunity. Some people know themselves well enough to admit:

“If I take that lump sum, I might keep it in cash out of fear . . . or I might overspend it in the first few years.”

If that’s you, the monthly pension may be the better fit. There is wisdom in knowing your personality.

It Depends on Your Entire Financial Picture

Like almost everything in personal finance, the right answer is:

It depends.

Specifically, it depends on:

  • When you plan to retire
  • How much you’ve saved outside the pension
  • Your Social Security strategy
  • Your income needs
  • Your comfort with volatility
  • Your tax situation

For example, if your pension would represent your only conservative income source, locking in that 5% growth until 65 and using it as your “safe money” might make sense, allowing your 401(k) to stay invested more aggressively.

But if you already have other conservative assets or guaranteed income sources, taking the lump sum and investing it for growth could provide more long-term flexibility.

You cannot look at this decision in isolation. It must fit into the entire retirement blueprint.

The Key Takeaway

If you’re wondering what most advisors would personally choose? Most would lean toward the lump sum because of the control, growth potential, and legacy flexibility.

But here’s the more important truth:

The best choice for you depends entirely on your situation . . . your temperament, income needs, assets, goals and discipline.

This decision should not be made in a vacuum. It should be made within a comprehensive retirement income plan that coordinates your pension, 401(k), Social Security, taxes, and long-term objectives.

If you’d like help evaluating how this fits into your full financial picture, we’re happy to walk through it with you.

Peterson Wealth Advisors is a registered investment adviser. Information presented is for educational purposes only. Please consult a qualified financial advisor before implementing any strategy.

Lump Sum vs. Annuity: How to Choose for Your Intermountain Pension

Your Intermountain Healthcare Pension Plan comes with a choice you have to make. You can take a lump sum and keep control of your assets, or choose an annuity and turn them into a steady stream of payments.

Timing matters just as much, because starting now versus waiting can change both the value you receive and the role your benefits play in your retirement planning. Ultimately, the right decision depends on your personal circumstances and a thorough understanding of what each path trades away and what it preserves.

Your Two Core Choices: What You’re Really Deciding

Your Intermountain pension offer is a long-term structure choice. The option you select determines whether this benefit functions more like a steady cash flow or a flexible asset.

Monthly Annuity (Lifetime Income)

Electing the monthly annuity converts your benefit into fixed monthly payments that continue for life. The amount is determined by age and actuarial assumptions at election. Once the stream begins, it is governed by the annuity contract and cannot be adjusted.

The appeal is predictable lifetime income. The limitation is that the payment is level. Intermountain’s pension plan does not provide cost-of-living adjustments, which means purchasing power declines over time when inflation persists. Over a 25- or 30-year retirement, that erosion can materially affect spending flexibility.

Structure also affects payout. A single life annuity provides the highest monthly amount but ends at your death. A joint and survivor election reduces the payment in exchange for continuing benefits to a spouse. That structural tradeoff directly impacts household income security.

Lump Sum (A Transferable Asset)

The lump sum represents the present value of your earned benefit, calculated using interest rate assumptions and life expectancy factors. Pension lump sums are highly sensitive to prevailing interest rates, which influence how future payments are discounted into today’s dollars.

This path creates flexibility. The asset can typically be rolled into an individual retirement account (IRA), integrated with your 401(k), invested according to your allocation strategy, and drawn upon based on your personal income needs. You control timing, tax sequencing, and how this capital fits into your overall retirement savings.

The tradeoff is responsibility and market exposure. Future income depends on allocation, withdrawal discipline, and portfolio performance. There is no contractual guarantee. Instead of a fixed payment schedule, you manage an asset whose outcome reflects investment returns and risk management over time.

Rollover Strategy and Tax Mechanics: Where Precision Matters

A rollover election can be clean and tax-deferred, or it can turn into an avoidable tax problem. The difference often comes down to how the paperwork is processed and where the funds are sent. Below, we’ll cover the mechanics that often cause problems.

Direct Rollover vs. Distribution

A direct rollover sends the lump sum straight from the pension plan to your IRA (or other eligible retirement account). Because the money never lands in your hands first, it typically keeps its tax-deferred status and avoids automatic withholding.

If the plan cuts the check to you instead, it is treated as a distribution even if you plan to redeposit it later. In many cases, that triggers mandatory federal withholding, so the amount you receive can be smaller than the total you meant to roll over.

Mandatory Withholding and Early Withdrawal Penalties

When the lump sum is paid to you rather than sent as a direct rollover, two issues occur: withholding and potential penalties. Both can change how much cash you actually have available to move.1

Eligible rollover distributions paid to you are generally subject to mandatory 20% federal withholding. Additionally, if you take taxable dollars out before age 59½, you may owe an additional 10% tax unless an exception applies.2

What Can and Cannot Be Rolled Over

Most eligible lump sum distributions from employer retirement plans can be rolled over to an IRA or another eligible plan.

Ongoing pension income is different. Once you elect an income form that starts paying out as a stream, those periodic amounts are generally treated as taxable payments to you, not a balance that can be rolled over in a single transfer. This distinction is one reason the rollover decision often needs to be made before payments begin.

Understanding Integration Strategy

A rollover is only step one. The bigger win is deciding how this new account fits into a coordinated retirement-income plan, so it supports cash flow, taxes, and risk management rather than sitting in a silo. A strong rollover integration strategy typically involves:

Account placement: Fold the rollover into the accounts you already have, such as your 401(k) and existing IRAs, so your overall allocation stays intentional, and you avoid ending up overexposed (or underexposed) by accident.

Withdrawal sequencing: Plan future distributions around federal tax brackets, Medicare-related income thresholds (IRMAA), and the timing of other income sources so withdrawals stay proactive and tax-aware.

Understanding required minimum distributions (RMDs): Traditional IRA balances generally have RMD requirements beginning at age 73 (with the starting age scheduled to increase to 75 in 2033 for those born in 1960 or later), which can increase future taxable income if you do not plan for them.

Reviewing Roth IRA conversions: Strategic conversions can sometimes reduce future RMD pressure by shifting dollars from pre-tax accounts into a Roth bucket, but the tax cost and side effects should be modeled before acting.

Portfolio role clarity: Define what this asset is meant to do inside your plan, such as flexible spending, later-life income support, or a legacy reserve, and invest and draw it down in a way that matches that purpose.

A Structured Decision Framework: Matching the Option to Your Retirement Design

The goal is not to pick the “right” option in a vacuum. The goal is to choose the option that fits the way you plan to live, spend, and provide for others.

Define What You Want This Benefit To Do

Some want their pension to function like a personal paycheck that keeps showing up, even if markets are down or plans change. Others want it to behave like an asset that can be shaped around spending needs, tax planning, and long-term goals. Getting clarity on what you want this benefit to do will ground the election and keep the decision practical.

The option that best serves you can depend on the importance of the following:

  • Covering baseline expenses like housing, utilities, and insurance
  • Creating flexible spending capacity for travel, hobbies, and family support
  • Reducing pressure on withdrawals from investments in the early years
  • Providing a backstop for later years when spending patterns may change
  • Protecting a spouse from an abrupt drop in household cash flow
  • Building a buffer for healthcare and long-term care costs
  • Supporting charitable giving goals
  • Leaving a legacy to children or grandchildren

Decide Which Tradeoff You Are Willing To Live With

Once you define the job you want your benefits to do, line them up against your options and the trade each one asks you to accept. Annuitizing now tends to fit households that want income to start immediately and stay steady, while giving up some ability to adjust later if spending priorities change.

Taking the lump sum now tends to fit households that want control right away and plan to coordinate withdrawals with the rest of their accounts, while accepting that the long-term outcome depends on disciplined management and a consistent withdrawal approach.

Model The Decision The Way You Will Live It

Modeling turns a permanent election into a decision you can defend. It replaces guesswork with a set of scenarios that reflect your household, not generic averages. The best models also show how the plan behaves when conditions are inconvenient.

Important things to model and consider include:

  • Your baseline monthly spending and what must be covered no matter what
  • How income changes when one spouse dies, and what replaces it
  • Expected inflation and how a level payment holds up later in retirement
  • A longer-life scenario that reflects the possibility of living well past averages
  • Taxes year by year, including brackets and how withdrawals stack with other income
  • RMD timing and how it affects taxable income later in retirement
  • Portfolio drawdown stress tests during down markets early in retirement
  • A legacy scenario that estimates what may remain for heirs under each option
  • A healthcare and long-term care stress test that reflects rising costs and changing needs

Lump Sum vs. Annuity for Your Intermountain Pension FAQs

1. How do I determine whether lifetime income or flexibility is more appropriate for my situation?

Start with the job you want this benefit to do. If you want to cover baseline expenses with a predictable check, a life annuity often supports that goal. If you want adaptability, tax planning control, and the ability to preserve remaining value for heirs, the pension lump approach tends to fit better. Your household budget, other income sources, and who will manage the money later all matter.

2. What are the tax consequences if I mishandle a lump sum distribution?

A mishandled lump sum payment can create unnecessary withholding, immediate taxable income, and possible early-distribution penalties depending on age. The clean approach is a direct rollover to avoid avoidable leakage, then a planned distribution strategy over time.

3. Can I change my mind after I elect the annuity or lump sum option?

In most cases, this is an irrevocable decision once the election is processed and the payments or rollover begin. That is why modeling up front matters. Treat the election like you would any other permanent financial commitment and make it with full context.

4. How does this decision affect my spouse or other beneficiaries?

The election affects survivor protection, the continuity of household cash flow, and what remains for heirs. A joint and survivor election can protect a spouse by continuing payments after the first death, while other elections may end at death or change benefit levels. Beneficiary goals and household income design should be discussed before you sign.

Helping You Make a Confident, Coordinated Pension Decision

Intermountain’s pension election is not a standalone form. It touches cash flow timing, taxes, survivor planning, and how much flexibility you will have in the years that follow. A clear plan brings those moving parts into one coordinated decision.

At Peterson Wealth Advisors, we work with Intermountain Health employees to compare each election path side by side, and translate the numbers into real-world outcomes. We build the strategy around your goals, your household, and your timeline, then integrate the election into your broader plan so it supports long-term stability and flexibility.

Don’t wait to get help exploring your options. If you want to see how your pension choices fit with the rest of your retirement picture, schedule a complimentary consultation with our team today.


Resources:

  1. https://www.irs.gov/retirement-plans/plan-participant-employee/rollovers-of-retirement-plan-and-ira-distributions
  2. https://www.irs.gov/taxtopics/tc557